

Contents
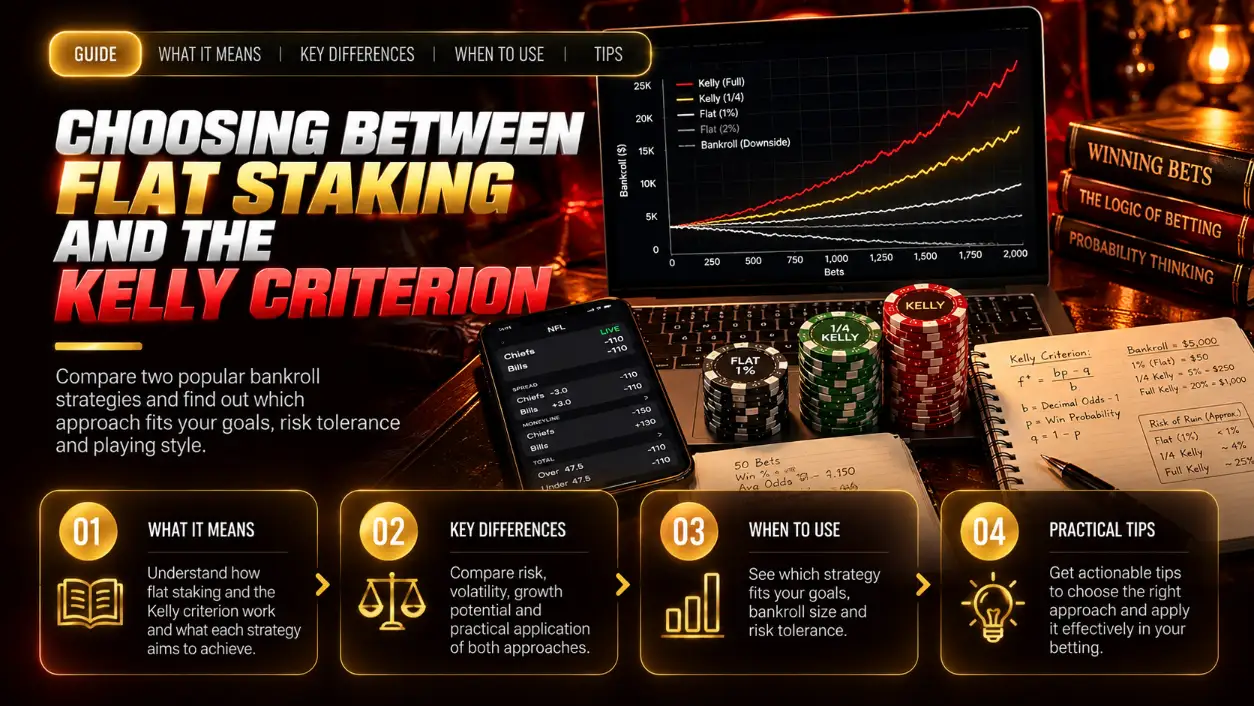
Use fixed-unit or percentage staking if you need a spending plan; use the Kelly criterion only when you have a justified outcome probability and available odds. A bankroll calculator is an interface, while Kelly is a stake-sizing rule that may be built into it. None of these methods creates a profitable edge.
Without a credible probability estimate, do not invent one to make the calculator produce a positive stake. An entertainment budget remains a spending limit when expected value is unknown or negative, not a way to generate profit.
Your bankroll is separate discretionary money allocated to betting. This guide compares stake-sizing methods, not your entire financial plan. For broader context, see what bankroll management means and the bankroll planning guide.
How the Four Staking Methods Differ
Fixed-unit staking keeps the cash amount constant, percentage staking keeps the fraction of your current bankroll constant, and full or fractional Kelly links that fraction to probability and odds. There is no universal winner or universally safe percentage.
| Method | What you enter or choose | Calculation base | How the cash stake changes | Main limitation |
|---|---|---|---|---|
| Fixed-unit staking | A cash unit and a review rule | A chosen constant amount | Stays unchanged until review | Takes up a larger share of the bankroll after losses |
| Percentage staking | Current bankroll and chosen percentage | Current bankroll | Falls after a loss and rises after a win | The percentage alone establishes neither an edge nor safety |
| Full Kelly | Bankroll, probability and odds | Calculated fraction of current bankroll | Changes with the bankroll and input estimates | Highly sensitive to probability errors |
| Half or quarter Kelly | The same inputs and a multiplier of 0.5 or 0.25 | The corresponding portion of full Kelly | Changes like full Kelly, but with a smaller stake | Reduces the stake without correcting the model |
A fixed stake of $10 is 1% of a $1000 bankroll. If the bankroll falls to $800, the stake remains $10—now 1.25%. A percentage stake of 1% becomes $8 at a bankroll of $800.
A unit is a chosen reference cash stake. It does not mean a universally safe 1–3% of your bankroll. If your aim is profit, fixed-unit staking also needs a justified process for selecting outcomes and odds.
How the Kelly Criterion Is Calculated
For a single binary bet that either wins fully or loses the entire stake, the full Kelly bankroll fraction is f = (d × p − 1) / (d − 1). This calculation assumes no fees or pushes.
Consider this standalone hypothetical example:
- Bankroll:
B = 1000dollars. - Decimal odds:
d = 2. - Hypothetical win probability:
p = 0.55. - Loss probability:
q = 0.45. - Net profit per unit staked, excluding the returned winning stake:
b = d − 1 = 1.
Then f = (2 × 0.55 − 1) / (2 − 1) = 0.10.
| Option | Multiplier of full Kelly | Bankroll fraction | Stake |
|---|---|---|---|
| Full Kelly | 1 | 10% | $100 |
| Half Kelly | 0.5 | 5% | $50 |
| Quarter Kelly | 0.25 | 2.5% | $25 |
Quarter Kelly means 0.25 of the calculated full Kelly stake, not 0.25% of the bankroll.
The break-even probability here is 1 / d = 0.50. The edge is expected net return per unit staked: d × p − 1 = 10%. The difference p − 1 / d = 0.05 is a separate measure: a gap of 5 percentage points between the probability estimate and the break-even probability.
Under correct assumptions, full Kelly maximizes expected logarithmic bankroll growth. It does not maximize expected cash profit or minimize every measure of risk. The historical foundation is J. L. Kelly’s 1956 paper, pages 919–920. The numerical checks here are independent calculations under the stated conditions. See the Kelly criterion explanation for more detail.
Reproducing the Example in the Kelly Calculator
In the Kelly calculator, select decimal odds, enter 2.00, a probability of 55 and a bankroll of 1000, then choose quarter Kelly. Results update automatically; there is no separate calculate button.
- Select Decimal odds.
- Enter
2.00in the odds field. - Enter
55in Your win probability. - Enter
1000in Bankroll. - Under Kelly fraction, select Quarter.
English Kelly calculator inputs with odds of 2.00, a win probability of 55 and a bankroll of 1000
Local capture of the English Kelly calculator running on a local computer. This verifies the local interface, not the live website.
The result shows an edge of 10%, full Kelly of $100, half Kelly of $50 and quarter Kelly of $25. The selected stake is 2.50% of the bankroll.
English Kelly calculator result showing a 10% edge and a quarter Kelly stake of 25 dollars
Local capture of the English Kelly calculator result for the hypothetical inputs.
The 55% probability is hypothetical, not evidence of forecasting ability. You must update the bankroll and available odds manually; the calculator does not synchronize with your account.
The interface rounds cash values to whole dollars. Its displayed expected value of $3 therefore rounds the exact $2.50 for a $25 stake. This is neither an exact profit nor a promised result: expected value is the probability-weighted net cash outcome under the model.
How Probability Errors Change the Stake
Even a small change in probability can substantially change a Kelly stake. With the same $1000 bankroll and odds of 2, the values are:
| Probability | Edge | Full Kelly | Half Kelly | Quarter Kelly |
|---|---|---|---|---|
| 55% | 10% | $100 | $50 | $25 |
| 54% | 8% | $80 | $40 | $20 |
| 52% | 4% | $40 | $20 | $10 |
| 50% | 0% | $0 | $0 | $0 |
| 48% | −4% | $0 | $0 | $0 |
The zeros mean that this rule produces no positive stake. At a probability of 50%, the interface displays No edge here and hides the stake card rather than displaying a numerical zero.
English Kelly calculator showing No edge here at a probability of 50% and odds of 2.00
Local capture of the English Kelly calculator with no edge; the stake card is hidden.
Do not increase a guessed probability to manufacture an edge, even if the interface wording encourages you to change the estimate. Record predictions in advance in a betting log, check calibration—whether stated probabilities match observed frequencies—and test on comparable events outside the sample used for tuning. Neither 500 nor 1000 bets, nor a comparison with pre-event closing odds alone, proves an edge.
What You Give Up With Fractional Kelly
Half and quarter Kelly reduce the amount at risk, but also reduce expected logarithmic growth when the model is correct. In this example, quarter Kelly retains about 44% of that growth, not “almost all” of it.
For p = 0.55 and d = 2:
| Option | Expected logarithmic change per bet | Share of full Kelly's result |
|---|---|---|
| Full Kelly | 0.50084% | 100% |
| Half Kelly | 0.37526% | About 75% |
| Quarter Kelly | 0.21879% | About 44% |
Logarithmic change accounts for the successive multiplication of the bankroll. It differs from expected value in dollars and does not show your future balance after the next bet.
If you estimate the probability at 55% but the true probability is 52%, continuing to stake 10% of the bankroll produces expected logarithmic growth of −0.10118%, despite positive expected cash profit. Overbetting can harm long-term growth even when expected value is positive. Fractional Kelly reduces the stake but does not correct an inaccurate probability.
What Ten Consecutive Losses Would Do
In a deliberately selected sequence of ten losses, fixed $10 stakes leave $900, while quarter Kelly at 2.5% of the current bankroll leaves $776.33. This is conditional arithmetic, not a forecast of how often such a run will occur.
The starting bankroll is $1000. For percentage-based methods, the odds and estimates remain unchanged. There is no intermediate rounding; final amounts are displayed to the nearest cent.
| Method | Stake | Bankroll after ten losses |
|---|---|---|
| Fixed-unit staking | $10 | $900.00 |
| Percentage staking | 1% of current bankroll | $904.38 |
| Full Kelly | 10% of current bankroll | $348.68 |
| Half Kelly | 5% of current bankroll | $598.74 |
| Quarter Kelly | 2.5% of current bankroll | $776.33 |
Percentage-based staking uses B_n = B_0 × (1 − f)^n; fixed cash stakes use B_n = B_0 − n × s, where s is the cash stake.
The chart shows one deliberately specified sequence. It is not a Monte Carlo simulation, a median, a forecast, or a probability of ruin or a losing streak. Drawdown here is measured from the chosen starting peak of $1000.
After the first quarter Kelly loss of $25, the bankroll is $975. The next stake is $24.375, or approximately $24.38 before applying the permitted stake increment.
Original capital-growth formula on page 919 of Kelly's 1956 paper
J. L. Kelly, 1956, page 919: the original formula V_N = (1 + l)^W (1 − l)^L V_0. The image preserves the original language and notation.
In that notation, V_0 and V_N are the starting and ending bankrolls, W and L are the numbers of wins and losses, and l is a constant bankroll fraction at odds of 2. These are historical symbols, not translated or modern interface labels.
When to Use the Broader Bankroll Calculator
The bankroll calculator helps compare methods using common inputs; the Kelly calculator is more direct for a single binary bet because it accepts probability explicitly. The broader calculator's edge input is not a probability input.
To reproduce the comparison:
- Select Sports betting.
- Enter a bankroll of
1000and select US dollars. - Enter an expected edge of
10%. - Set average odds to
2. - Select the Flat % method button, then enter
1in the displayed flat-percentage field. - Select the Fractional Kelly method button and click 0.5×. You may return to Flat % to reproduce the displayed table; the comparison retains these parameters.
The comparison shows units of $10, $50 and $100 for percentage staking, half Kelly and full Kelly respectively.
Cropped English bankroll calculator comparison showing method columns and units of 10, 50 and 100 dollars
Local capture of the English bankroll calculator showing methods and cash units, not a verification of the live website.
Enter 10% edge, not 55% probability, in the edge field. Sports betting mode derives probability using p = (1 + e) / d, where e is the edge expressed as a fraction. These inputs produce 55%, but the calculator does not establish whether that estimate is credible.
The percentage field displayed under Flat % specifies a percentage of the entered bankroll, not a permanently fixed cash amount. Risk figures, 95% drawdown figures, time-to-double estimates and green indicators rely on unverified preset approximations. They are not calibrated personal forecasts or endorsements of safety. See the risk of ruin guide for the limits of such estimates.
Applying the Calculation Within Your Limits
Use a calculated stake only within your personal spending limit and the combined amount at risk across open bets. The calculator does not replace those limits.
- Define the available base. Use only allocated discretionary money. Do not count funds committed to open bets twice or include future winnings.
- Set a personal cap. For example, an illustrative limit of 2% of $1000 means $20, capping the calculated quarter Kelly stake of $25. This is a manual limit, not a tool feature or a recommendation of a safe percentage.
- Add up the combined risk. Account for bets on the same event and all open positions. They share one bankroll; fixed-unit staking does not remove outcome dependence either.
- Update the calculation. A change in odds, bankroll or justified probability requires a stake review.
- Check the minimum and stake increment. If the minimum stake or permitted increment would force you above your cap, skip the bet rather than round up.
- Account for actual payout terms. Fees require the actual net payout. Pushes, half wins, half losses or multiple possible payouts require a complete outcome distribution or a justified calculation using conditional probabilities. Do not insert them blindly into the binary model.
The tool for calculating Kelly stakes jointly assumes independent outcomes and does not optimize correlated bets. Reducing each individual stake is not a substitute for checking combined risk.
What the Built-In Questionnaire Can Tell You
The built-in questionnaire helps you consider your preferences, but it does not calculate a personalized mathematical stake. It uses preset answers about confidence, risk tolerance, experience and time horizon rather than actual odds, probability and bankroll.
Its result neither confirms an edge nor certifies that any percentage is safe. If you lack a justified probability, start with a spending limit and review rules for fixed-unit or percentage staking. If your probability is justified, test its sensitivity, calculate the Kelly fraction and manually apply your personal cap and limits on the total amount at risk.
Frequently Asked Questions
Recalculate when your current bankroll, available odds or justified probability estimate changes. For fixed-unit staking, set a review point for the cash unit in advance. Account for money already committed to open bets separately, and do not include future winnings in your available funds.
Yes. In ideal arithmetic, staking less than 100% of the bankroll does not reduce it to zero over a finite losing sequence, but the remaining balance may fall below the minimum stake or your stopping threshold. Estimating risk of ruin requires that threshold, a time horizon, staking rules and an outcome model that accounts for dependence.
No. The number of bets alone does not establish the quality of a probability model. You need predictions recorded in advance, calibration checks and results on comparable events outside the sample used to tune the model. Comparing your odds with pre-event closing odds is not independent proof of an edge either.
With negative expected value, the model does not justify a positive stake for profit. Slot return-to-player percentages or an overall poker win rate cannot be used as the probability of a single binary outcome. An entertainment budget limits spending but does not change negative expected value.
Evgeniy Volkov
Verified ExpertFullstack developer with a background in mathematics. I build the calculators and game-style tools on ToolsGambling with Pixi.js and modern web tech, and every result uses transparent probability formulas you can verify yourself.