


Contents
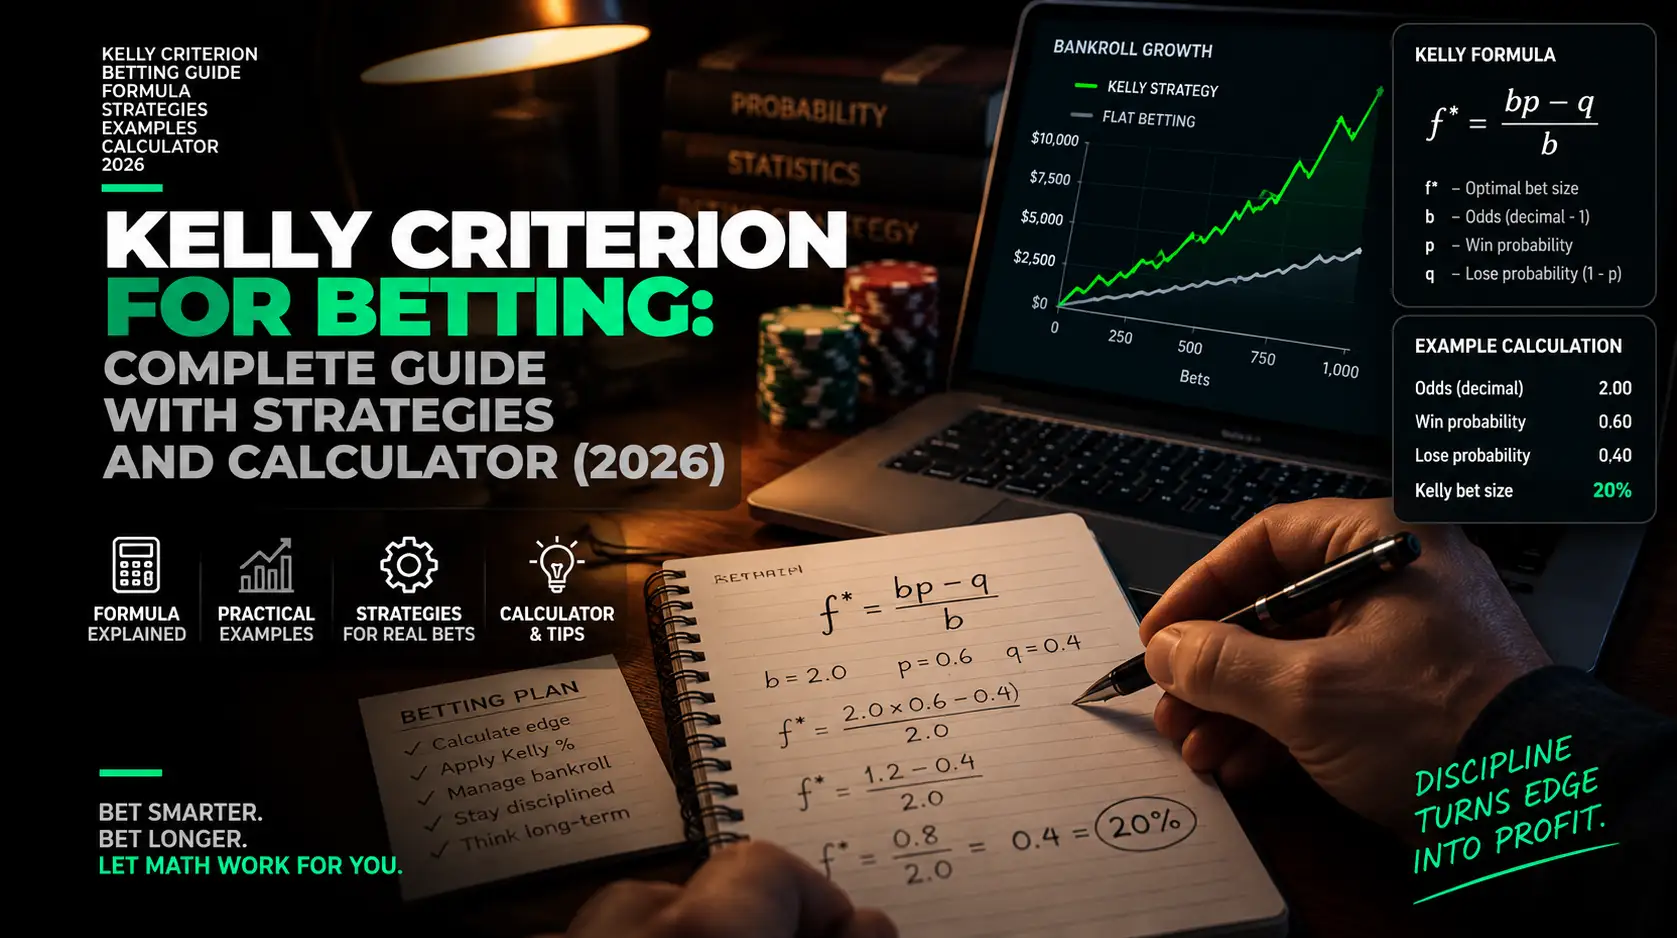
The Kelly criterion sizes bets from odds and your estimated win probability to maximize expected logarithmic bankroll growth under the model. It does not estimate that probability for you or guarantee a profit.
Its purpose is to choose a fraction of capital—not predict the winner, ensure the next bet wins or eliminate drawdowns. The logarithmic objective comes from Kelly’s 1956 paper; this is a mathematical foundation, not evidence of profitable modern sports betting.
Here, your bankroll means a separate gambling budget you can afford to lose. It excludes money needed for essential expenses. The bankroll management guide explains how to set those boundaries.
What inputs does the Kelly formula need?
For a binary bet that either wins or loses, Kelly needs decimal odds and an estimated probability of winning.
The variables are:
- : the full Kelly fraction of your bankroll;
- : decimal odds, including the return of your stake;
- : net profit per unit staked when the bet wins;
- : win probability, entered as for 55%, not ;
- : loss probability.
The formula assumes , no fees or pushes, and a complete loss of the stake when the bet loses. A positive stake requires a probability above the break-even threshold .
Decimal odds of 2.10—also +110 in American odds and 11/10 in fractional odds—have an implied probability of 47.62%. With an estimated win probability of 55%, the probability gap is 7.38 percentage points, while the edge, expressed as expected net profit per unit staked, is 15.5%:
These are different measures: the probability gap is not the expected return on the amount staked. See what edge means in betting for the distinction.
The chosen stake is:
Here, is your current available bankroll, and is the multiplier of full Kelly: for full, for half and for quarter Kelly. 50% of full Kelly does not mean 50% of your bankroll. A practical risk cap can reduce the resulting stake further, including to zero.
Worked example: a $1000 bankroll at odds of 2.10
Full Kelly gives a stake of $140.91, half Kelly gives $70.45, and quarter Kelly gives $35.23 when the estimated win probability is 55%.
This illustrative example assumes binary settlement, no fees or pushes, and an available bankroll of $1000. It is not a measured sports-betting edge. Full Kelly allocates 14.09% of the bankroll. The table displays calculated amounts and percentages to two decimal places; the underlying model uses unrounded values.
| Setting | Multiplier of full Kelly | Bankroll fraction | Calculated stake | On-screen amount |
|---|---|---|---|---|
| Full Kelly | 100% | 14.09% | $140.91 | $141 |
| Half Kelly | 50% | 7.05% | $70.45 | $70 |
| Quarter Kelly | 25% | 3.52% | $35.23 | $35 |
At half Kelly, a win leaves a bankroll of $1077.50, while a loss leaves $929.55. These outcomes use the unrounded stake: a winning payout returns the stake plus net profit, while a losing bet forfeits the stake.
Expected value (EV), expressed as expected net profit, is $10.92:
That is not an actual profit. A single bet either wins or loses.
Recalculate stakes using current available capital after settlement. Money reserved for unsettled bets is not free capital for new bets. If a minimum stake or rounding up would exceed your chosen limit, skip the bet rather than increase exposure to reach a convenient amount.
How do full, half and quarter Kelly differ?
Full Kelly maximizes expected logarithmic growth when the model inputs are true; half and quarter Kelly reduce the stake and the impact of losses, but neither is universally safe.
For an actual bankroll fraction , expected logarithmic growth is:
The corresponding geometric factor per bet, in percent, is:
With constant true probability and decimal odds , the example produces:
| Setting | Expected logarithmic growth | Geometric factor per bet |
|---|---|---|
| Quarter Kelly | 0.004772 | 0.4783% |
| Half Kelly | 0.008177 | 0.8211% |
| Full Kelly | 0.010909 | 1.0969% |
These are long-run geometric factors for a model of repeated independent bets with identical inputs. They are not arithmetic ROI per bet, a forecast of your bankroll or guaranteed growth.
The checked illustrative model below also shows what happens when stakes exceed full Kelly. It is not a Monte Carlo performance comparison of betting strategies.
| Multiplier of full Kelly | Geometric factor per bet |
|---|---|
| 0 | 0% |
| 0.25 | 0.4783% |
| 0.5 | 0.8211% |
| 1 | 1.0969% |
| 1.5 | 0.8155% |
| 2 | −0.0450% |
At 1.5 times full Kelly, model growth is already below the optimum. At twice full Kelly, it is negative: −0.0450%, not exactly zero. Increasing the stake does not keep increasing growth.
How should you estimate probability and account for errors?
Use a current model tested on out-of-sample data or reliable, comparable records; an arbitrary number of bets or a single win cannot establish an edge.
Check calibration: do predicted probabilities match outcome frequencies on new data? Account for changes in lineups, conditions and available prices. Closing prices with the bookmaker margin removed—devigged prices—can provide a benchmark, but they are not known true probabilities. Positive closing line value (CLV) alone does not prove profitability.
The paper on modified Kelly criteria examines probability uncertainty and adjustments to sizing. The limited practical takeaway is that plugging an inaccurate estimate into full Kelly can produce an excessive stake.
At decimal odds of 2.10, sizing is sensitive to the probability input:
| Estimated win probability | Raw full Kelly bankroll fraction | Model decision |
|---|---|---|
| 45% | −5.00% | No bet |
| 47.62% | 0% | No bet |
| 50% | 4.55% | Positive fraction |
| 52% | 8.36% | Positive fraction |
| 55% | 14.09% | Positive fraction |
The 47.62% row represents the exact threshold , rounded for display. A negative fraction is capped at zero; it does not automatically become a lay bet.
An estimation error can even change the sign of geometric growth. If the true win probability is 50%, odds of 2.10 still offer a +5% edge. But staking 14.09% of the bankroll, based on the mistaken 55% estimate, produces a geometric factor of −0.3883%. The optimal bankroll fraction at the true 50% probability is only 4.55%.
If the probability is unknown, or you simply use , you have no evidence of a positive edge and no justified positive Kelly stake. Fractional Kelly cannot repair negative expected value. Establish a defensible value bet before deciding its size.
What drawdowns can Kelly produce?
Kelly does not eliminate losing streaks or risk of ruin; a smaller fraction reduces the impact of each loss, all else equal.
A conditional stress scenario of ten consecutive losses, with each stake recalculated from the current bankroll, follows:
Starting with $1000 and using the example’s unrounded fractions:
| Setting | Bankroll after ten losses |
|---|---|
| Full Kelly | $218.97 |
| Half Kelly | $481.62 |
| Quarter Kelly | $698.63 |
This is a conditional stress scenario, not a probability of ruin or a forecast of the next sequence. Even when proportional stakes do not mathematically reduce capital to exactly zero in a finite number of losses, your balance can fall below minimum stakes or your acceptable loss limit.
Different sizing methods address different objectives:
| Method | Sizing rule | Required inputs | Main limitation |
|---|---|---|---|
| Fixed amount | Stake the same monetary amount | Available budget and stake limit | The stake becomes a larger bankroll fraction after losses |
| Fixed current-bankroll fraction | Stake a chosen percentage of available capital | Current bankroll and chosen percentage | The percentage alone does not account for edge |
| Kelly criterion | Set the fraction from probability and odds | Probability estimate, odds and bankroll | Probability errors can inflate the stake |
| Progression | Change the amount according to a rule after results | Progression rule and budget | It creates no edge and can run into limits |
None guarantees a profit. Increasing your stake after a loss does not improve the odds, win probability, or expected profit per unit staked: the edge stays unchanged. It does change monetary expected value and exposure in proportion to the stake. A staking progression cannot create a positive edge.
How do you use the ToolsGambling Kelly calculator?
Enter decimal odds of 2.10, a win probability of 55% and a bankroll of $1000, then select Half; the calculator displays a recommended stake of $70 after whole-dollar rounding.
Open the Kelly calculator and use these controls:
- Enter 2.10 in Decimal odds.
- Enter 55 in Your win probability. This field accepts a percentage, unlike the formula’s .
- Enter 1000 in Bankroll, representing available dollars.
- Select Half under Kelly fraction for 50% of full Kelly.
Kelly calculator inputs showing odds of 2.10, a 55% win probability and a bankroll of 1000 dollars
English calculator screenshot from localhost: inputs and the Half selection.
Read the resulting values:
- Your edge: 15.50%;
- Implied: 47.62%;
- recommended bankroll fraction: 7.05%;
- recommended stake: $70;
- full Kelly stake: $141; quarter Kelly stake: $35;
- Expected value per bet: $11.
Kelly calculator result showing a 15.50% edge, a 7.05% bankroll fraction and a 70-dollar stake
English calculator screenshot from localhost: monetary results rounded to whole dollars.
The screen shows whole dollars, while the calculated values in the earlier table—$70.45, $140.91, $35.23 and $10.92—are displayed to cents. The model uses unrounded values internally. The 50% label describes the multiplier of full Kelly; 7.05% describes the bankroll fraction.
To test sensitivity, change Your win probability to 50. Half Kelly becomes 2.27% of the bankroll, with a calculated stake of $22.73 and an on-screen amount of $23. At 45, the interface shows No edge here rather than a numeric recommended stake; the model caps the stake at zero. Do not raise your probability estimate merely to obtain a positive result.
The calculator does not validate your probability, replace a forecasting model or guarantee future growth. Its verbal risk label is a heuristic, not a measured risk of ruin.
For the optional Monte Carlo simulation, enter 200 bets, 1000 trials and a 50% drawdown threshold, then click Run simulation. It uses independent Bernoulli win/loss outcomes at constant probability and odds, with stakes recalculated from current capital.
Maximum drawdown is measured from the running bankroll peak. Reaching 50% or less of the initial bankroll—$500 or less from an initial $1000—is a different measure. Although the interface calls that threshold “ruin,” it is neither literal zero nor an estimate of real-world risk of ruin. Random estimates change on reruns; they are not observed betting results or validation of your probability.
How should you handle simultaneous bets, parlays and pushes?
Simultaneous bets need a shared-bankroll allocation model; simply adding individual Kelly fractions can give the wrong combined exposure.
The calculator’s joint section supports up to eight independent bets, with no correlation input. Even independent bets share one bankroll and must respect a common capital constraint.
For example, two independent bets at decimal odds of 2 with 55% win probabilities each have a standalone full Kelly fraction of 10%. The joint calculation assigns 9.90% to each, totaling 19.80%, rather than 20%. These percentages are rounded for display.
Bets on the same match may be correlated or mutually exclusive. They require a different joint outcome model; the tool’s independence model does not apply. Simply scaling down separately calculated stakes is not a substitute for that model either.
A parlay requires the joint probability that all selections win. Multiplying individual probabilities is valid only when independence is justified.
A single selection in a three-way home-win/draw/away-win market can be treated as binary: the selection wins, or any other outcome occurs. A draw is not automatically a push; settlement depends on the bet’s rules.
For a full refund with no net profit or loss, use win and loss probabilities conditional on there being no refund. Half-wins, half-losses and other partial settlements require an expanded set of payoffs. If fees apply, use net profit after fees rather than inserting the quoted decimal odds without adjustment.
What should you check before placing a bet?
Bet only when the edge is defensible, the stake fits your risk limit, and available bankroll excludes money already reserved for other bets.
Before deciding, check:
- Probability evidence: Is the model current and tested on new data, rather than supported only by past wins?
- Conservative inputs: Could incomplete information or changed conditions have inflated the probability?
- Fraction and risk cap: Is full, half or quarter Kelly appropriate, or should a lower practical cap override it?
- Combined exposure: Have you accounted for unsettled bets and dependence between outcomes?
- Current calculation: Have the odds or available budget changed?
- Recordkeeping: Are you recording estimated probability, odds, stake and settlement so you can assess the model, not merely count wins?
If a key condition is missing, no bet is a valid decision. Do not increase stakes to chase losses: bet sizing cannot create an absent edge.
Frequently Asked Questions
The bet has no positive expected value at the entered odds and probability. The stake is capped at zero. A negative result does not automatically justify a lay bet.
Kelly does not create an edge. If a bet has negative expected value, a positive Kelly stake is not justified. Using a smaller fraction cannot fix a negative edge.
No. Full Kelly maximizes expected logarithmic growth only under the model’s correct assumptions. Probability errors, drawdowns and budget constraints can make that stake unacceptable.
No. Separate calculations do not account for the shared bankroll or dependence between outcomes. The calculator’s joint section supports independent bets only; related outcomes require a joint probability model.
For a full refund with no profit or loss, the binary calculation can use win and loss probabilities conditional on the bet not being refunded. Half-wins, half-losses and other partial settlements require an expanded payoff model.
Evgeniy Volkov
Verified ExpertFullstack developer with a background in mathematics. I build the calculators and game-style tools on ToolsGambling with Pixi.js and modern web tech, and every result uses transparent probability formulas you can verify yourself.