

Contents
Sports betting bankroll management means setting rules for an allocated budget: how much to stake, how much to expose at once, when to stop and how to record results. It helps control spending and risk, but it does not create an edge over a sportsbook.
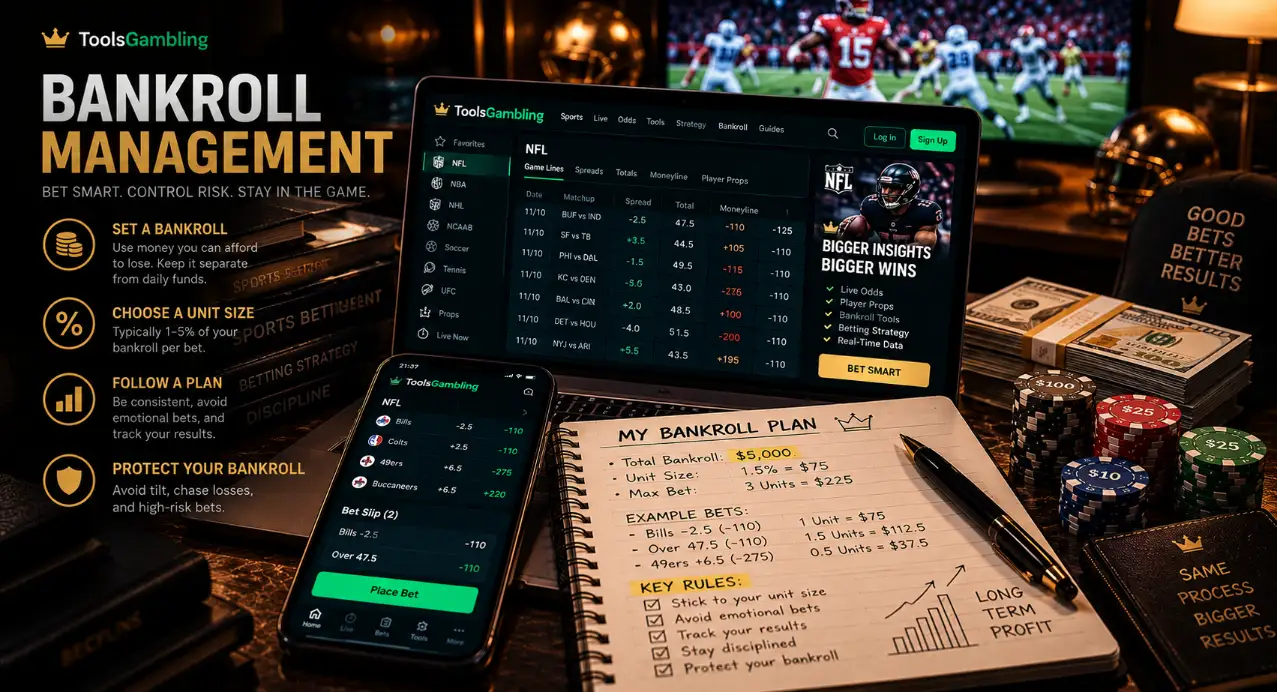
The repeatable process is straightforward: allocate money you can afford to lose, choose a stake size, set exposure and loss limits, and keep a betting log. Review the plan outside betting sessions. Your bankroll is neither your entire income nor a budget you must use up.
Set an affordable bankroll
Your bankroll should contain only money you can lose without affecting living expenses, debt payments or emergency funds. Exclude borrowed money and funds needed for essentials. There is no universal starting bankroll.
For a combined bankroll, add available funds and reserved stakes across all operators, counting each amount once. Exclude bonus funds because they may not be withdrawable.
For example, a $1000 bankroll can consist of $800 in available funds and $200 in unsettled bets. That is $1000, not $1200. If an operator balance already includes reserved stakes, do not add them again. A potential payout from a pending bet is not available cash.
An external top-up is not net profit. It simply changes the amount allocated to betting.
Minimum stakes can make a plan impractical. With a $50 bankroll, a $1 stake is 2%. If your personal cap is 0.5%, the permitted stake is $0.25. Skip the bet or keep a practice log without money rather than increasing your budget to satisfy the operator’s minimum.
The broader bankroll management guide explains how to separate gambling funds from other money.
Calculate your unit and stake size
A unit is your chosen reference stake. To calculate it as a share of your bankroll, use unit = B × r, where B is the bankroll and r is the chosen fraction expressed as a decimal.
| Bankroll | 0.5% | 1% | 2% |
|---|---|---|---|
| $500 | $2.50 | $5 | $10 |
| $1000 | $5 | $10 | $20 |
| $5000 | $25 | $50 | $100 |
These fractions are illustrations, not certified safe stake sizes or recommendations for earning income. A $1000 bankroll with a $10 unit contains 100 units, but that number does not guarantee survival.
Choose a reset policy in advance. You might hold a fixed cash stake until a scheduled review, or recalculate a percentage stake from a specified base after bets settle. Do not increase stakes because of emotion, chasing losses or subjective “confidence.” The bankroll unit calculation guide provides further arithmetic examples.
Choose a staking method
Flat staking keeps the cash amount unchanged, percentage staking follows a specified bankroll base, and the Kelly criterion also requires an estimated win probability. None of these methods makes an otherwise unprofitable bet profitable.
| Method | Cash rule | Required inputs | Response to losses | Limitations |
|---|---|---|---|---|
| Flat or level staking | For example, $10 until a predeclared reset | Fixed stake, bankroll and limits | The stake stays unchanged and becomes a larger share of the reduced bankroll | Requires a reset policy and open exposure controls |
| Percentage staking | For example, 1% of the current settled base | Current base and chosen fraction | The stake falls as the base shrinks | Minimum stakes, rounding and simultaneous bets constrain its use |
| Kelly criterion | A calculated fraction based on odds and probability | Decimal odds d, estimated probability p, bankroll base and constraints | With unchanged inputs, the cash stake falls with the base | Probability errors change the output; a personal stake cap may be lower |
For percentage staking, define how unsettled bets affect the base. One reproducible approach is to use the bankroll balance established by settled results, minus money already reserved in open bets. Do not include expected payouts or reuse funds already committed.
In the examples below, each cash bet settles before the next is placed, so there are no overlapping open bets. This assumption isolates the difference between staking methods; it does not describe every real betting session. A percentage stake that never mathematically reaches zero is not a safety guarantee: minimum stakes and practical bankroll boundaries still apply.
Understand what a losing streak does
Stake size materially changes the size of a loss. Over ten consecutive losses, flat staking deducts the same cash amount each time, while percentage staking deducts a fraction of the remaining base.
Starting with $1000, compare the same initial stake fractions:
| Initial fraction | Fixed cash stake | Balance after flat staking | Balance after percentage staking |
|---|---|---|---|
| 1% | $10 | $900 | $904.38 |
| 2% | $20 | $800 | $817.07 |
| 5% | $50 | $500 | $598.74 |
There are no wins, fees or voids in this example. Bets settle sequentially, and balances are rounded only at the end. The formulas are B − n × s for flat staking and B × (1 − r)^n for percentage staking, where B is the starting bankroll, n the number of losses, s the fixed stake and r the stake fraction.
The chart compares staking methods at matching initial fractions. It does not predict your future sequence of results.
Recovering a loss requires a larger percentage gain: a 20% loss requires a 25% gain on the remaining bankroll, while a 50% loss requires a 100% gain. Drawdown means a fall from a previous bankroll peak. Record transfers separately so withdrawals are not mistaken for drawdown caused by betting.
How likely is a long losing streak?
The probability depends on both the assumptions and the event being measured. With independent bets and an assumed win probability of p = 0.53, the probability of losing the next eight bets is 0.47^8 = 0.2381%.
The probability of at least one eight-loss run anywhere within 200 bets is 21.90896%, using an exact finite-state calculation. That is a different event: the run can start in many places, and possible runs overlap.
An assumed 53% win probability is not evidence of skill. Dependence between results changes the model. Variance describes variation in outcomes; it cannot be reduced to a universal multiplier for each sport.
A risk of ruin calculation needs a failure boundary, time horizon, odds, probabilities, stake rules and assumptions about correlation. “100 units is safe” has no universal meaning without those conditions.
Use the Kelly criterion only with a probability estimate
The Kelly criterion calculates a stake fraction from odds and your estimated win probability. If you do not have a defensible estimate, skip it: a sportsbook’s implied probability does not establish your edge.
For a binary cash bet with a win or loss and no fees, the formula is:
f = max(0, (d × p − 1) / (d − 1))
Here, f is the full Kelly fraction, d is decimal odds and p is win probability expressed as a decimal. With a known or assumed model probability, the criterion maximizes long-run logarithmic growth, not expected money. That is a model objective, not a personal recommendation. The historical foundation appears in Kelly’s 1956 paper.
At decimal odds of 2.00, a 55% win probability and a $1000 bankroll:
- Full Kelly is 10%, or $100.
- Half Kelly is $50.
- Quarter Kelly is $25, or 2.5% of the bankroll.
Quarter Kelly means one quarter of the calculated stake, not automatically 0.25% of the bankroll. At a 52% probability, quarter Kelly in this example is $10. At 50%, it is zero.
At odds of 2.00 and an assumed 55% probability, expected value (EV) is 0.1 times the stake. This is expected net profit under the model, not a measured result or a confirmed edge.
Enter the example in the calculator
In the Kelly calculator, enter the odds, your probability estimate and bankroll, then select a quarter of the calculated stake. For this example:
- Choose Decimal as the odds format.
- Enter
2.00in Decimal odds. - Enter
55in Your win probability. - Enter
1000in Bankroll. - Press Quarter.
English Kelly calculator interface with decimal odds 2.00, win probability 55 and bankroll 1000
Localhost capture of the English interface with example inputs. This is not a real wager or verification of a production betting transaction.
Results update automatically. The selected stake is $25, or 2.50%; the Full result is $100, Half is $50 and Quarter is $25.
English Kelly calculator interface showing a quarter Kelly stake of 25, or 2.50% of the bankroll
Local interface capture showing the result for an assumed 55% win probability, not a recommendation to stake money.
Change only Your win probability to 52 and review the $10 result, then change it to 50 and review zero. This shows how sensitive the calculation is to the probability estimate.
The interface’s risk badge is not a recommendation. Your personal stake cap can be lower than the calculated result, and open bets require a separate exposure check.
Account for price and open exposure
The price determines the win probability needed to break even; open exposure shows how much you could lose on bets already placed. A single win-rate target cannot apply to all odds.
Without fees, break-even probability is 1 / d, where d is decimal odds. For example, American odds of −110 correspond to decimal odds of 1.90909: you risk $110 to win $100 in net profit.
The break-even probability is 52.38%. At an assumed 50% win probability, EV is −$5 per $110 stake; at 53%, it is +$1.30. This is arithmetic based on an assumed probability, not a prediction of its true value.
For more on price notation, see how betting odds work.
Add exposure across all operators and track each event separately. With a $1000 bankroll, ten open $10 bets expose $100, or 10%. Three $10 bets on the same game expose $30, or 3%.
Different sportsbooks do not make those bets independent. For overlapping events, track the stakes and scenarios in which bets could lose together.
For example, you could test a personal policy with these limits:
- Total open exposure: no more than 5% of the bankroll.
- Exposure to one event: no more than 2%.
These are illustrative personal limits, not research-established safe values. With a $1000 bankroll, ten open $10 bets breach the first limit, and three $10 bets on one game breach the second. You do not need to bet up to a quota.
Futures can tie up cash for a long time. Live betting can stack exposure quickly. Parlays and longshots have different win frequencies, and parlay legs may be correlated. There is no universal rule that they require three times as much capital.
For lay bets, liability can exceed the displayed stake. Use the maximum amount you could owe if the bet loses, not just the stake shown.
Keep a betting log and measure results consistently
A betting log should separate settled results, open exposure and money transfers. Otherwise, deposits can look like profit and gross returns can be mistaken for net profit.
For each bet, record:
- Date, market and sportsbook.
- Odds and stake.
- Status and gross return, including the winning stake.
- Any void refund.
- Net profit or loss.
- Open exposure.
- A comparable closing price, if you track one.
Record deposits, withdrawals and fees separately.
Here is an example of five $10 cash bets:
| Bet | Decimal odds | Outcome | Gross return | Void refund | Net profit or loss |
|---|---|---|---|---|---|
| 1 | 2.00 | Win | $20 | — | +$10 |
| 2 | 1.80 | Loss | $0 | — | −$10 |
| 3 | 1.90 | Win | $19 | — | +$9 |
| 4 | 2.10 | Loss | $0 | — | −$10 |
| 5 | 2.00 | Void | — | $10 | $0 |
The net result is a $1 loss. A starting bankroll of $1000 becomes $999, assuming no other money flows.
Including the voided stake gives turnover of $50 and yield of −2%. Counting only bets with decided outcomes gives turnover of $40 and yield of −2.5%. The return on the starting bankroll is −0.1%.
Choose your convention for including voided stakes in turnover before reporting results, and use it consistently. If you use the label ROI, state the denominator explicitly: turnover or starting bankroll. They measure different things.
Two of the four decided bets won, a 50% win rate, but the different prices produced a loss. This short example demonstrates accounting, not representative performance.
What does CLV tell you?
Closing line value (CLV) measures how the odds you took compare with a comparable closing price—the odds available just before the event begins. It indicates whether you secured a better or worse price, but does not guarantee skill or future profit.
Compare the same market, threshold and settlement rules at a defined closing time. Changed conditions can make prices incomparable. There is no fixed sample size after which CLV automatically proves an edge.
Write your limits before betting
Put your budget, stake size, exposure caps, pause conditions and review policy into a short personal plan before placing bets. A rule chosen in advance is easier to repeat than one invented after a loss.
An illustrative one-page plan for a $1000 bankroll could look like this:
| Item | Personal rule for this example |
|---|---|
| Unit | $10 |
| Total open exposure | No more than 5%, or $50 |
| Exposure to one event | No more than 2%, or $20 |
| Daily realized loss | At $30, pause and place no new bets |
| Before another bet | Check the worst-case loss on unsettled bets, including futures |
| Deposits | Set a personal monthly maximum based on affordability |
| Review | Review on a schedule, outside play; reduce stakes after a material bankroll decline |
These values are not research-established safe limits. A stop rule controls new exposure, not the payouts or EV of existing bets. Unsettled stakes can still lose, so pausing does not guarantee an immediate cap on the final loss.
Do not use martingale doubling to recover losses. Starting at $10, six consecutive losses cost $630; the next stake is $640. The total required is $1270, more than a $1000 bankroll.
Distinguish deposit limits, loss limits and stake caps
A deposit limit restricts money paid in, a loss limit restricts losses under specified rules, and a stake cap restricts one bet’s exposure. They do not replace each other, an affordability limit or a time limit.
Separate sportsbook accounts do not enforce your overall budget either. You still need consolidated records.
For operators regulated in Great Britain, the current UKGC RTS 12 standard, last updated 30 September 2026, requires financial-limit facilities at registration and periods of 24 hours, 7 days and one month. Reductions take effect immediately except during technical failure; increases require at least 24 hours and confirmation. A gross deposit limit counts deposits without deducting withdrawals, so withdrawing money does not restore that allowance. These requirements apply within the relevant Great Britain regulatory framework, not to every operator worldwide.
If you are chasing losses, borrowing to bet or cutting essential spending, stop and seek appropriate local help. The NHS gambling support page is an English-language resource with help routes for England; it is not a worldwide support service.
Interpret the embedded bankroll calculator cautiously
The embedded calculator below is for exploring rough scenarios under preset assumptions. Its outputs do not confirm an edge, provide calibrated risk of ruin probabilities or forecast maximum drawdown or time to double a bankroll.
Unit size depends on the selected profile: the hobbyist preset uses 1.25%. The assumed edge is modified by an internal factor and a floor. Its sport multiplier is arbitrary, not an empirical ranking of profitability or risk.
Do not use this block’s output to justify funding a bankroll, increasing stakes or expecting income. The repeatable parts of your plan are an affordable budget, a clearly defined calculation base, consolidated open exposure and a betting log. If a new bet fails any of your limits, you can simply skip it.
Frequently Asked Questions
Calculate the minimum stake as a share of your bankroll. With a bankroll of $50, a $1 minimum stake is 2%, while a 0.5% cap allows only $0.25. If those conditions conflict, skip the bet or keep a practice betting log without money. Do not increase your budget to meet the operator’s minimum.
Not automatically. Resize your unit only under a rule chosen in advance, such as a scheduled review after a material bankroll change. A winning streak does not establish an edge or override your exposure limits.
Record them separately from betting results. An external top-up increases your allocated bankroll but is not net profit. A withdrawal reduces that bankroll but is not a betting loss. After either change, check your unit size and open exposure limits.
Combine available funds and reserved stakes across all operators, counting each amount once. Maintain an overall open exposure limit and a separate limit for each event. Using different sportsbooks does not make bets on the same game independent.
The Kelly criterion requires a defensible estimate of your win probability. The probability implied by the odds is not a substitute and does not establish an edge. If you have no estimate, skip Kelly. Flat staking does not create an edge either.
Evgeniy Volkov
Verified ExpertFullstack developer with a background in mathematics. I build the calculators and game-style tools on ToolsGambling with Pixi.js and modern web tech, and every result uses transparent probability formulas you can verify yourself.